All-In-One Construction Accounting Software

Three Entities, One Job: Why Construction CFOs Outgrow QuickBooks Enterprise

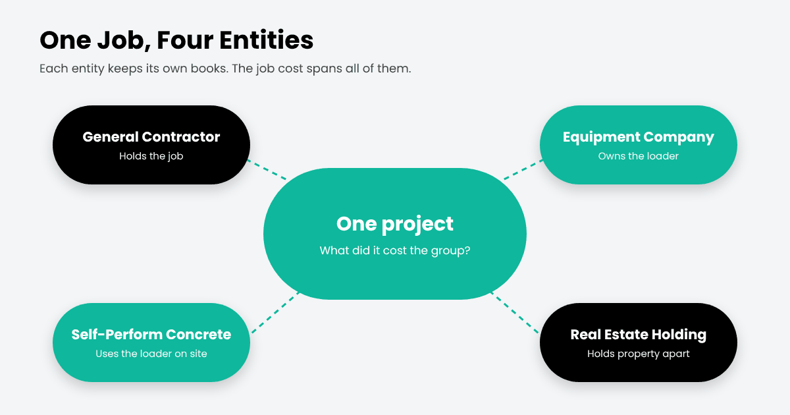
Four entities. One project. The general contractor holds the job. A related equipment company owns the loader. A self-perform concrete company uses it on site.

Now the CFO has a simple question: What did this project cost the group?

In QuickBooks Enterprise, those companies may sit in separate company files. Equipment charges move between entities, while project costs need to stay tied to the job. Across dozens of projects, month-end can become a reconciliation exercise before the CFO sees the full job cost.

QuickBooks Enterprise can combine certain reports across company files. But Intuit’s documentation limits that feature to standard statements and trial balance reports, with matching account names and Excel as the output. Job cost reports aren’t included in Enterprise’s built-in Combine Reports feature.

That’s the real issue. Multi-entity job costing isn’t a month-end consolidation task. The cost needs to stay connected to the job as transactions move across entities.

In short

Multi-entity job costing tracks project costs across several legal entities with shared cost codes and automated intercompany entries. QuickBooks Enterprise keeps each entity in a separate file and combines only summary financial reports, so group-level job costs are usually rebuilt in spreadsheets.

Why Contractors Run Multiple Entities

Few mid-size contractors operate as a single company for long. Common reasons include:

  • Liability separation: keeping risky work or regions in their own entity.
  • Equipment companies: owning fleets separately and renting internally.
  • Self-perform or specialty subsidiaries: concrete, electrical, or site work under their own license.
  • Real estate and development: holding property apart from operations.

Each reason makes sense. Together, they turn one project into several sets of books.
Why Contractors Run Multiple Entities

Where QuickBooks Enterprise Runs Out

QuickBooks Enterprise can handle accounting within each company. The challenge comes when you need to connect those companies around the same construction project:

  • Separate company files: each entity maintains its own company file, with its own jobs and cost codes.
  • Limited combined reporting: selected financial reports can be combined across company files, subject to matching account structures and Excel output.
  • Intercompany transactions: Platinum and Diamond support intercompany transactions between related company files, but each entity still maintains its own company records.
  • No unified cross-entity job view: the key question is not simply whether transactions can move between companies. It is whether the CFO can see the true cost and profitability of a project across the group.

One Loader, Three Sets of Books

Here’s how a single internal rental plays out when each entity keeps its own books :
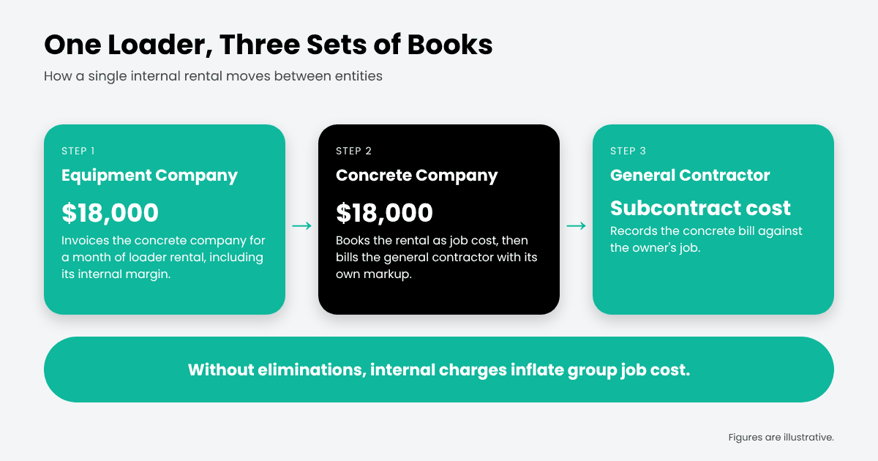
Each company’s books can be correct, but the group-level job view can still be distorted. The equipment company records rental revenue, while the concrete company records the rental as a project cost. Without a clear intercompany trail and elimination process, those internal charges can inflate the group’s apparent job cost and distort project profitability.

What Multi-Entity Job Costing Actually Requires

Before evaluating any system, construction CFOs should check for these five capabilities:

What you need Why it matters to a construction CFO
Intercompany that posts once An equipment rental or labor charge between entities is entered one time and balances both sets of books.
One cost code structure across entities A concrete cost code means the same thing in every company, so job costs roll up cleanly.
A group-level view of each job You can see what a project costs the whole group, not just the entity that holds the contract.
Committed costs and WIP by entity Subcontracts, POs, and WIP are tracked where they belong, ready for lenders and sureties.
Consolidation with traceable intercompany Every intercompany entry is tagged to a partner, so eliminations are easy to find and review.

Modern ERP platforms handle much of the accounting side. In Microsoft Dynamics 365 Business Central, for example, intercompany partners enter information once, and “a corresponding document is created at the other partner.” Microsoft is also candid that consolidation eliminations remain a manual step, which is why tagging every intercompany entry matters.

The Netsmartz View: Design Entities Around the Job

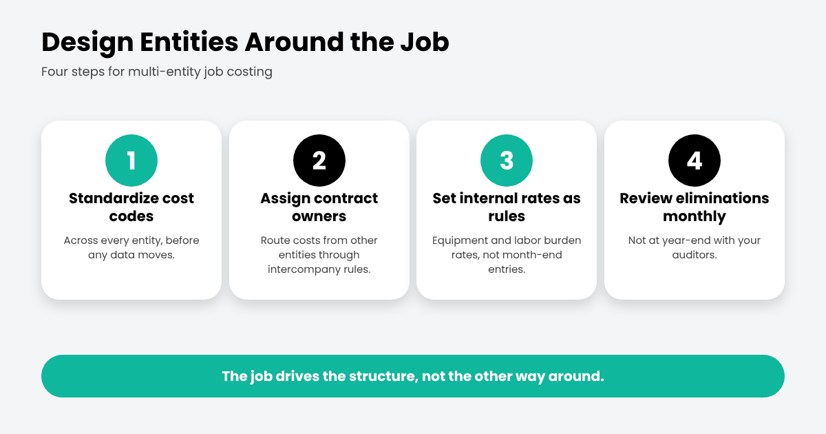
Most multi-entity pain comes from setting up entities for legal reasons and hoping job costing follows. Flip it:
The Netsmartz View: Design Entities Around the Job

Where ProjectPro Comes In

ProjectPro is Netsmartz’s all-in-one, AI-powered construction ERP built on Microsoft Dynamics 365 Business Central. It brings construction job costing and financial management into one platform, with Microsoft 365 Copilot as the intelligence layer.
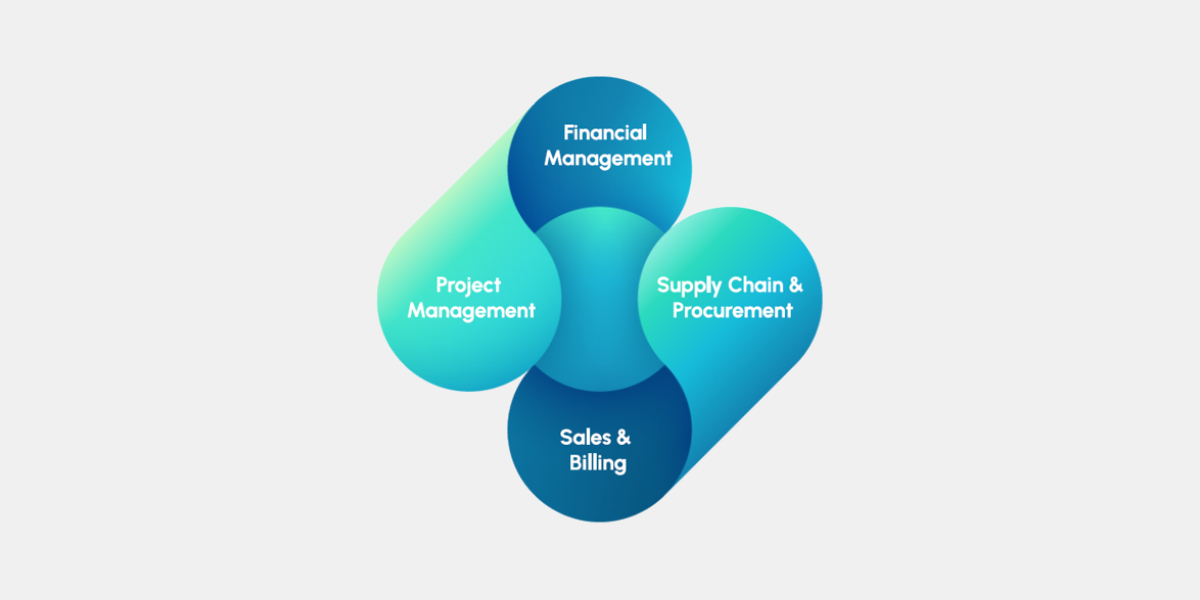
For multi-entity contractors, ProjectPro brings these requirements into one construction ERP environment. It combines construction job costing by project, phase, and cost code with intercompany accounting, labor and equipment resource management, subcontracts, retention, progress billing, and WIP.

Each company can maintain its own books while finance and project teams work from connected project and financial data across the group. That gives CFOs a clearer view of what each entity owns, what it owes, and what each project actually costs across the organization
CTA

The Bottom Line

QuickBooks Enterprise can tell you how each company did. A growing contractor also needs to know how each job did across all of them. When that answer lives in a spreadsheet, the structure has outgrown the software.

See how multi-entity job costing works in ProjectPro. Take the product tour.

Frequently asked questions

Multi-entity job costing tracks construction project costs across two or more legal entities, such as a general contractor, self-perform subsidiary, and equipment company. A shared cost code structure helps finance teams see project costs and profitability across each entity and the group.

QuickBooks Enterprise can combine selected financial reports from multiple company files into Excel, including balance sheet, profit and loss, cash flow, and trial balance reports. The company files must use matching account names, types, and levels. Its built-in Combine Reports feature does not include job-cost reports or provide a project-level view of costs across entities.

In Microsoft Dynamics 365 Business Central, you can assign intercompany partners to customers and vendors. When one company sends an intercompany transaction, the corresponding document can be created in the partner company, reducing duplicate entry across entities.

The terms are often used interchangeably. Multi-company construction accounting generally refers to managing multiple companies or sets of books within an accounting system. Multi-entity job costing goes further by connecting project costs, commitments, and WIP across those companies, so finance teams can see each job’s cost across the group.

A common trigger is when multiple entities share jobs, equipment, or labor and group-level job costs, intercompany balances, or WIP have to be rebuilt in spreadsheets each month. That is a sign to evaluate whether the accounting system can support the way the business operates.

ProjectPro brings construction job costing, intercompany accounting, commitments, WIP, and project financials into the same ERP environment. Built on Microsoft Dynamics 365 Business Central, it helps construction companies track costs by project, phase, and cost code while maintaining separate company books.
Estimate to Budget Handoff: Your Budget Was Set Before You Won the Job

The day you win a bid, someone opens a new job and types in a budget. In most shops, nobody chooses what goes in. The estimate goes in, because it is the only number anyone has. That is the estimate to budget handoff, and it is a quiet decision with a long tail.

The estimate was built under a deadline, on one person’s judgment, to be competitive. From award day it becomes the yardstick for every cost report, change order and WIP schedule. If it carries a mistake, or a structure that does not match how you code costs, the job starts slightly out of true, and you spend months wondering why the margin keeps slipping.

Where the handoff goes wrong

Three patterns worth checking for your own jobs. They are things to look for, not statistics.

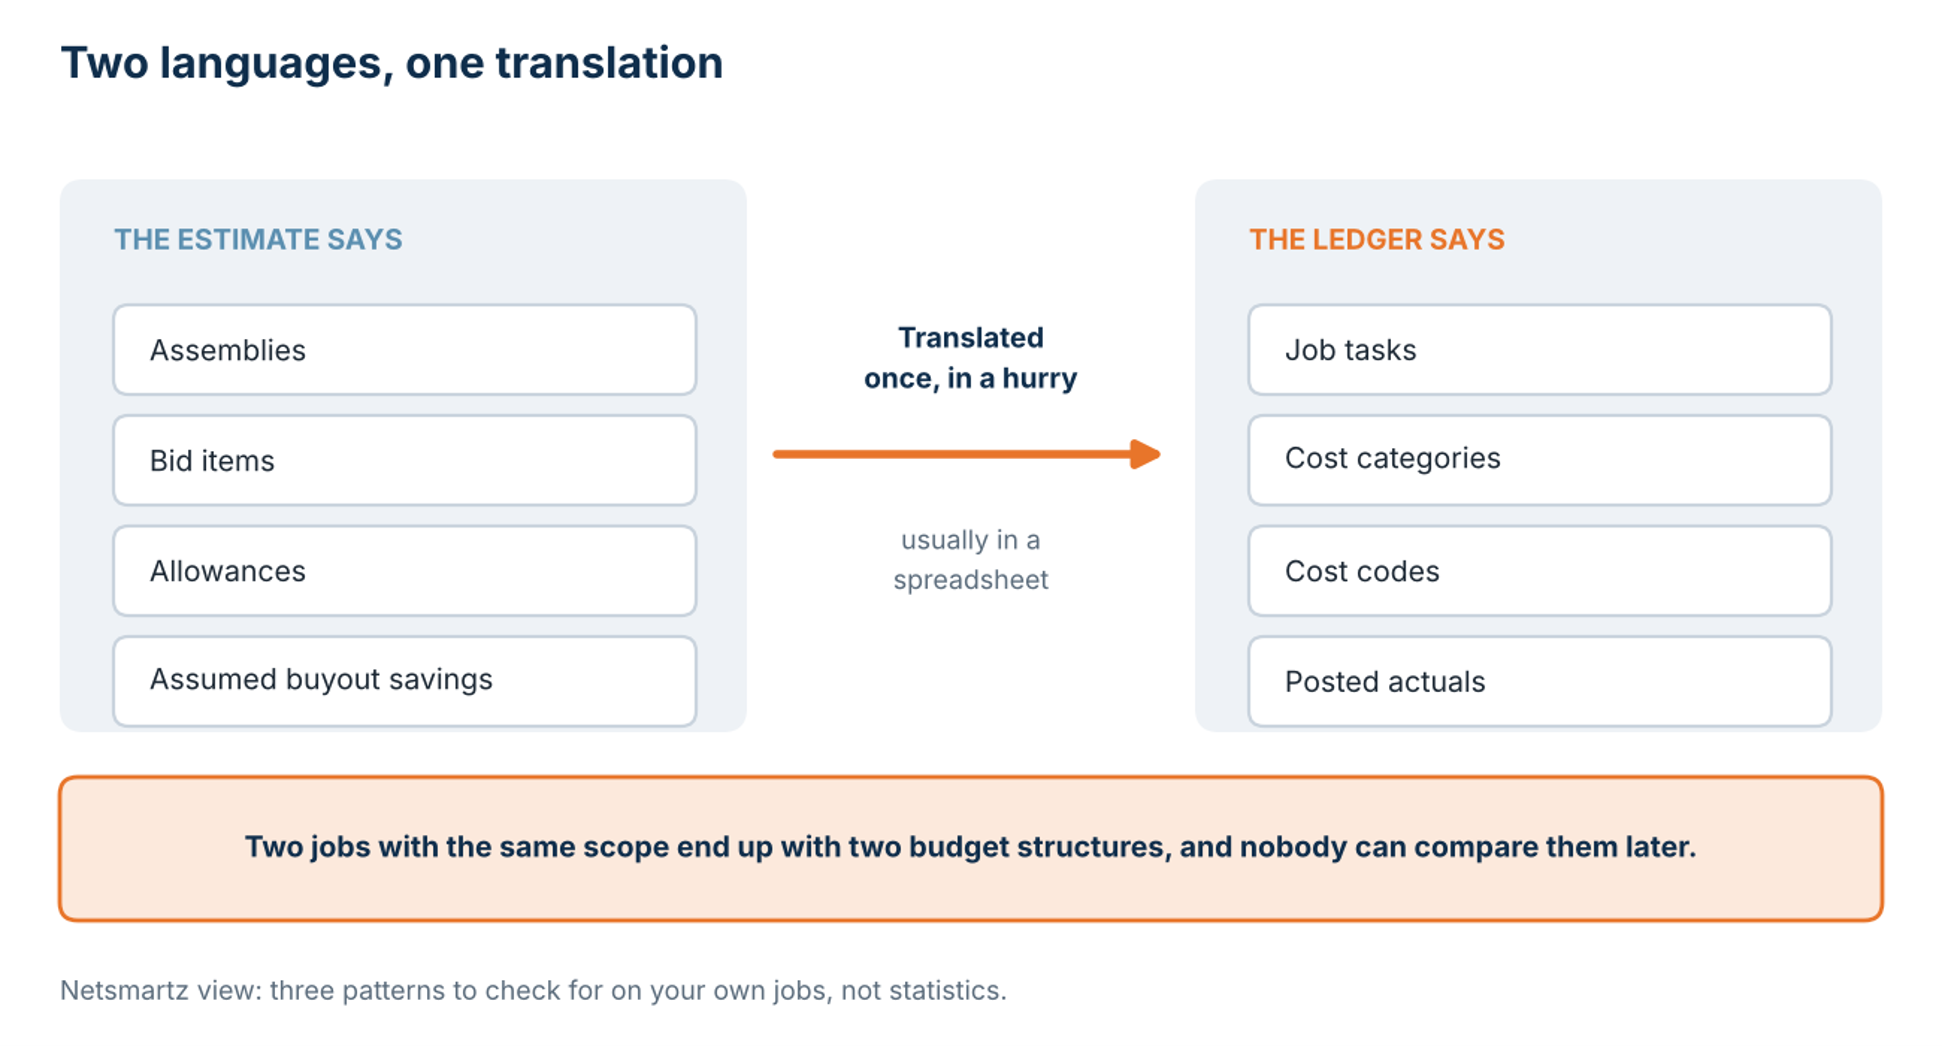
The estimate and the ledger speak different languages. Estimators think in assemblies and bid items. Accounting thinks in cost codes. Somewhere between award and the first purchase order, someone translates one into the other, usually in a spreadsheet, usually once, usually in a hurry. Two jobs with the same scope end up with different budget structures, and nobody can compare them later.

Where the handoff goes wrong

The translation that happens between award and the first purchase order.

The assumptions do not travel. The number makes it into the system. The reasons behind it do not: the allowance carried for a long-lead item, the savings counted on at buyout, the scope excluded from the proposal. Six weeks in, a project manager sees a variance and cannot tell whether it is a problem or just an assumption coming due.

There is no clean baseline to change. The first change order lands, and the question is whether it gets added to the budget or tracked beside it. If the original budget was never frozen, you are amending a moving target.

Underneath all three sits a simpler problem: the handoff has no owner. The estimator feels the job ended at award. Accounting feels it starts when the budget arrives. The project manager inherits whatever lands between them. Nobody is careless. The task simply belongs to nobody.

A small example, invented for illustration. The estimate carries an allowance for switchgear because the supplier has not quoted yet. Six weeks after award the quote comes in higher. If the allowance was never written down, the project manager see an overrun on electrical equipment and starts asking the field what went wrong. If it was written down, the same number is a known assumption coming due, and the conversation is about buyout instead of blame.

An estimate to budget handoff that takes thirty minutes

You do not need new software to try this on your next award.

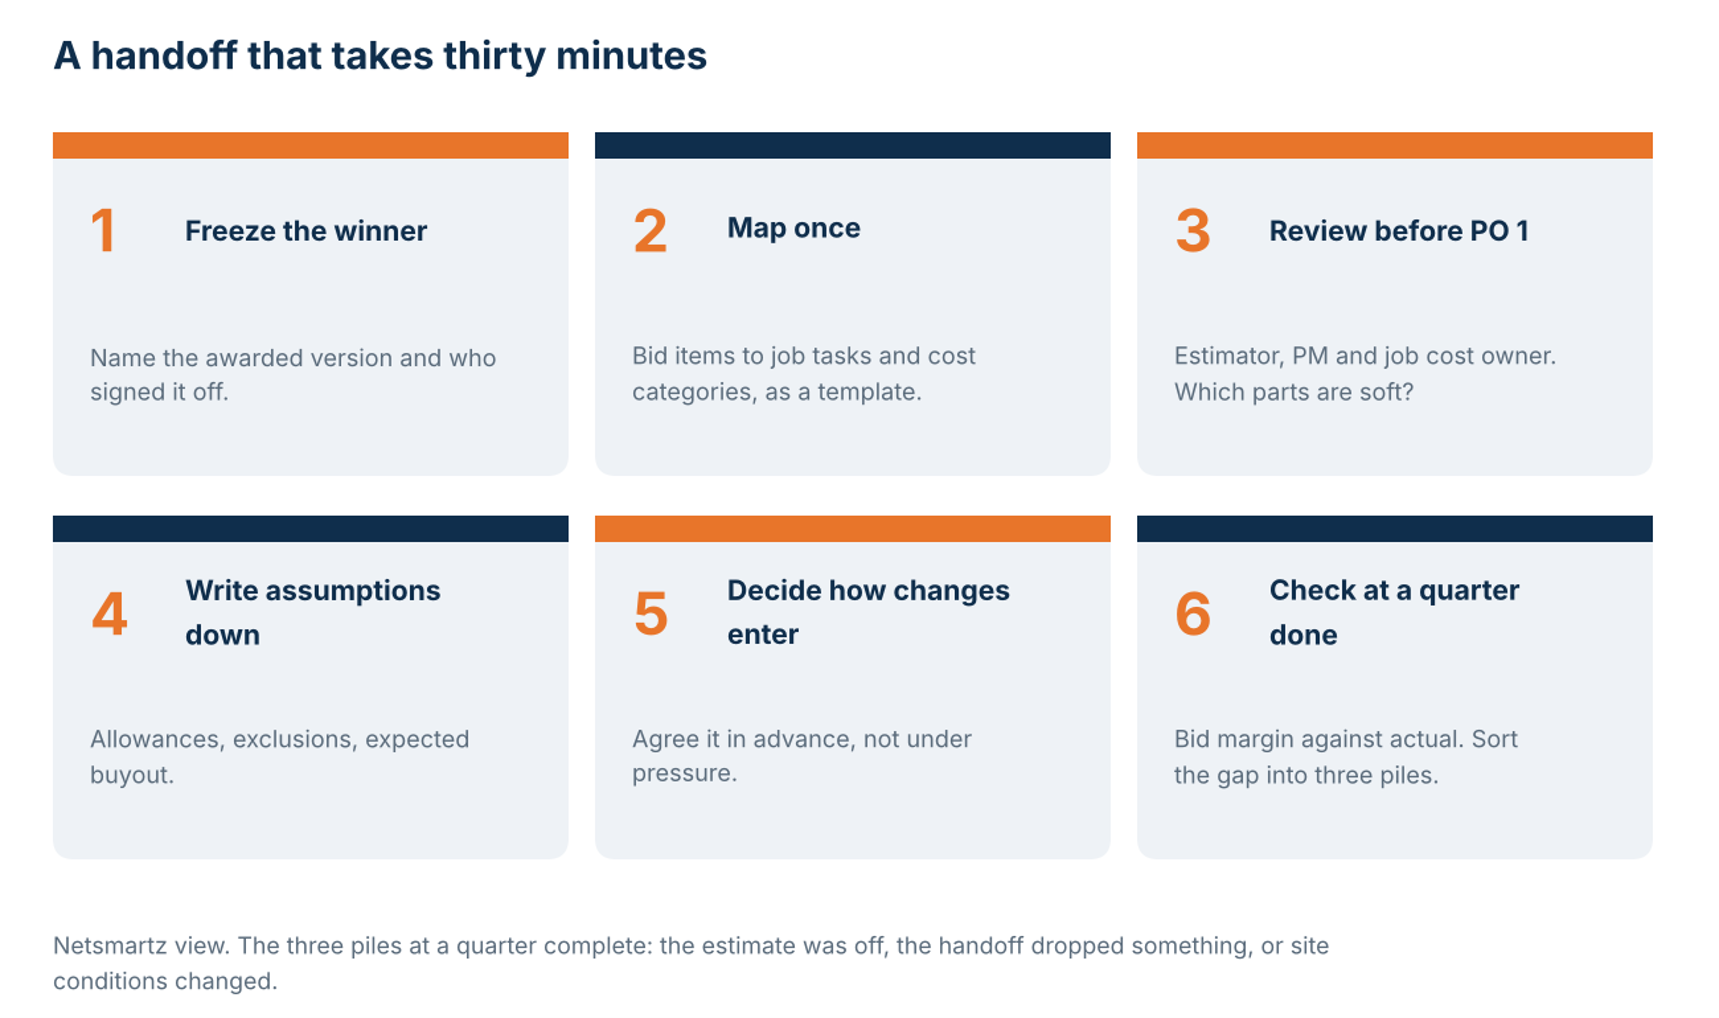
  1. Freeze and name the version that won. “Awarded estimate, signed off by [name], [date]” beats “final_v3_revised”.
  2. Map bid items to job tasks and cost categories once, as a template, not job by job.
  3. Hold a short review before the first purchase order: estimator, project manager and whoever owns job cost. The estimator’s job in that meeting is to say which parts of the number are soft.
  4. Write the assumptions down beside the budget: allowances, exclusions, expected buyout.
  5. Decide in advance how approved changes enter the baseline, so you are not deciding it under pressure.
  6. At roughly a quarter complete, compare actual margin with bid margin. Sort each gap into three piles: the estimate was off, the handoff dropped something, or site conditions changed. The middle pile is the one you can fix.

An estimate to budget handoff that takes thirty minutes

The six steps. Run them whatever you estimate in.

Why the baseline matters in Business Central

ProjectPro is built on Microsoft Dynamics 365 Business Central, so it helps to know how Business Central treats a budget. A project budget is built from planning lines on each task. Every line has a type: Budget, Billable, or Both. The budget is compared with actual usage posted to the project. And according to Microsoft’s documentation, Budget-type usage “is used to calculate WIP.”

So a wrong baseline does not stay on the budget screen. It flows into the WIP schedule, which is a document your bonding company and your bank may ask to see. The handoff is not a back-office detail.

From estimate to WIP schedule. The Microsoft quotation is from Learn; the bank and surety point is our inference.

Where ProjectPro fits

ProjectPro’s job quoting page describes quotes built from bid items, job tasks and assemblies of labor, equipment and subcontract cost. It describes quotes that convert into jobs, and a view of budgeted versus actual cost by bid item. When the quote and the job live in the same system, there is less to retype at award, and retyping is where handoff errors tend to start.

Software can carry the numbers across. Someone still has to say which of them are soft. Run the thirty-minute review either way.

See how a quote becomes a job in ProjectPro

Book a demo and bring your last job awarded. We will walk through how the quote, the budget, and the cost report connect.

FAQs

It is the moment an awarded estimate becomes the operating budget for a job. It is where structure, assumptions and ownership change hands.

Usually the estimate is the starting point. The questions are what has changed since the bid, such as buyout results and scope clarifications, and whether you want to keep the bid margin visible next to a separate operating budget. That is a policy choice, and a good one to make on purpose.

The frozen version of the budget that every later cost report, change order and WIP schedule is measured against. Without one you are comparing actuals to a moving target.

No. The steps above work whatever you estimate.

Certified Payroll Is Where Construction ERPs Quietly Fail

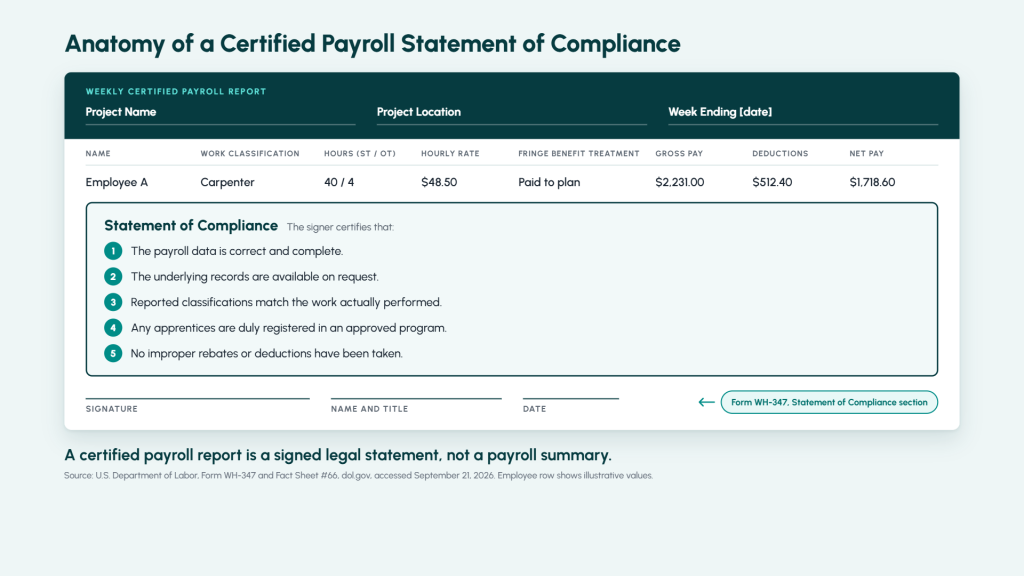
A certified payroll report ends with a signature, not a submit button. On the Statement of Compliance section of Form WH-347, someone at your company certifies that a specific week’s hours, wage rates, classifications, fringe benefits, and deductions are accurate for every worker on a federally funded job, and that the underlying records are complete and available on request. Get that wrong often enough and it stops being a paperwork problem.

Certified payroll, the weekly reporting required on Davis-Bacon and state prevailing wage jobs, is not a payroll run with extra fields. It demands a weekly cadence instead of biweekly, wage rates that shift by trade and county, fringe benefit math with its own annualization rules, apprentice ratios tracked against a registered program, and a report format that depends on which government agency is asking. Most construction ERPs were built around job costing and billing, not around that list, and certified payroll got added later, if it got added at all.

What a Certified Payroll Report Actually Has to Prove

The Department of Labor’s Fact Sheet #66, covering the Davis-Bacon and Related Acts, is direct about the cadence: contractors on covered jobs pay workers weekly and submit weekly certified payroll records to the contracting agency, not monthly, not at the end of the job. Each report covers one project, one pay period, and every laborer or mechanic who touched the site that week.

The document that carries the legal weight is the Statement of Compliance, the signed section of Form WH-347. It is not a summary. Signing it certifies that the payroll data is correct and complete, that the underlying records will be produced on request, that each worker’s reported classification matches the work actually performed, that any apprentices are properly registered in a bona fide program, and that no rebates or improper deductions were taken from anyone’s pay. Five separate certifications, one signature, every week, for the life of the project.

The Department of Labor released an online fillable version of the WH-347 in December 2025, alongside an annotated guide, specifically to cut down on the errors contractors were making on the paper form. Wage and Hour Division Administrator Andrew Rogers framed it as a tool to “improve accuracy, reduce administrative burden, and promote consistent reporting practices across DBRA-covered projects.” The web version is optional. The underlying obligation, submitting accurate weekly data under a signed certification, is not, and has not changed.

Fringe Benefits Are Where Davis-Bacon Compliance Gets Complicated

A Davis-Bacon wage determination sets a base hourly rate and a fringe benefit rate, and a contractor can satisfy the fringe portion in cash, through a bona fide benefit plan, or some combination of both. That flexibility is useful. It is also where the math stops being simple.

The Department of Labor’s Fact Sheet #66E lays out the mechanics. Credit for a fringe benefit plan is based on the annualized rate of contribution, meaning a contractor has to average what it pays into that plan across all hours an employee works during the year, Davis-Bacon and non-Davis-Bacon hours alike, not just the hours on the certified job. Benefits expressed as a percentage of the base rate do not automatically carry into overtime calculations the same way cash wages do. A contractor’s own administrative cost of running the benefit plan is not creditable against the fringe obligation. And whether a given payment counts as a fringe benefit or as straight wages changes how overtime gets calculated on that check.

None of that shows up as a validation error in a general ledger. A payroll system built for a standard biweekly cycle has no built-in reason to track annualized contribution rates or flag a benefit that is structured as a percentage instead of a flat dollar amount. It just runs the numbers it is given.

Apprentice Ratios Are a Prevailing Wage Reporting Trap

Apprentices can legally be paid less than the prevailing wage rate on a covered job, but only inside a specific limit. Department of Labor guidance is precise about it: an apprentice can be paid below the wage determination rate only if the ratio of apprentices to journey workers on site does not exceed the ratio set by the apprentice’s registered program, or by the standards for the locality where the project sits, if that differs from where the program is registered.

That is a headcount rule, tracked daily, on a jobsite where crews move between tasks and subcontractors bring their own people. Exceed the ratio and the apprentices working above it are owed the full journeyworker rate retroactively, not a warning. Most systems that track labor hours were not built to flag a ratio breach in real time. They log hours by employee and classification, and the ratio math happens later, if it happens at all.

Why the WH-347 Form Isn’t the Only Certified Payroll Form

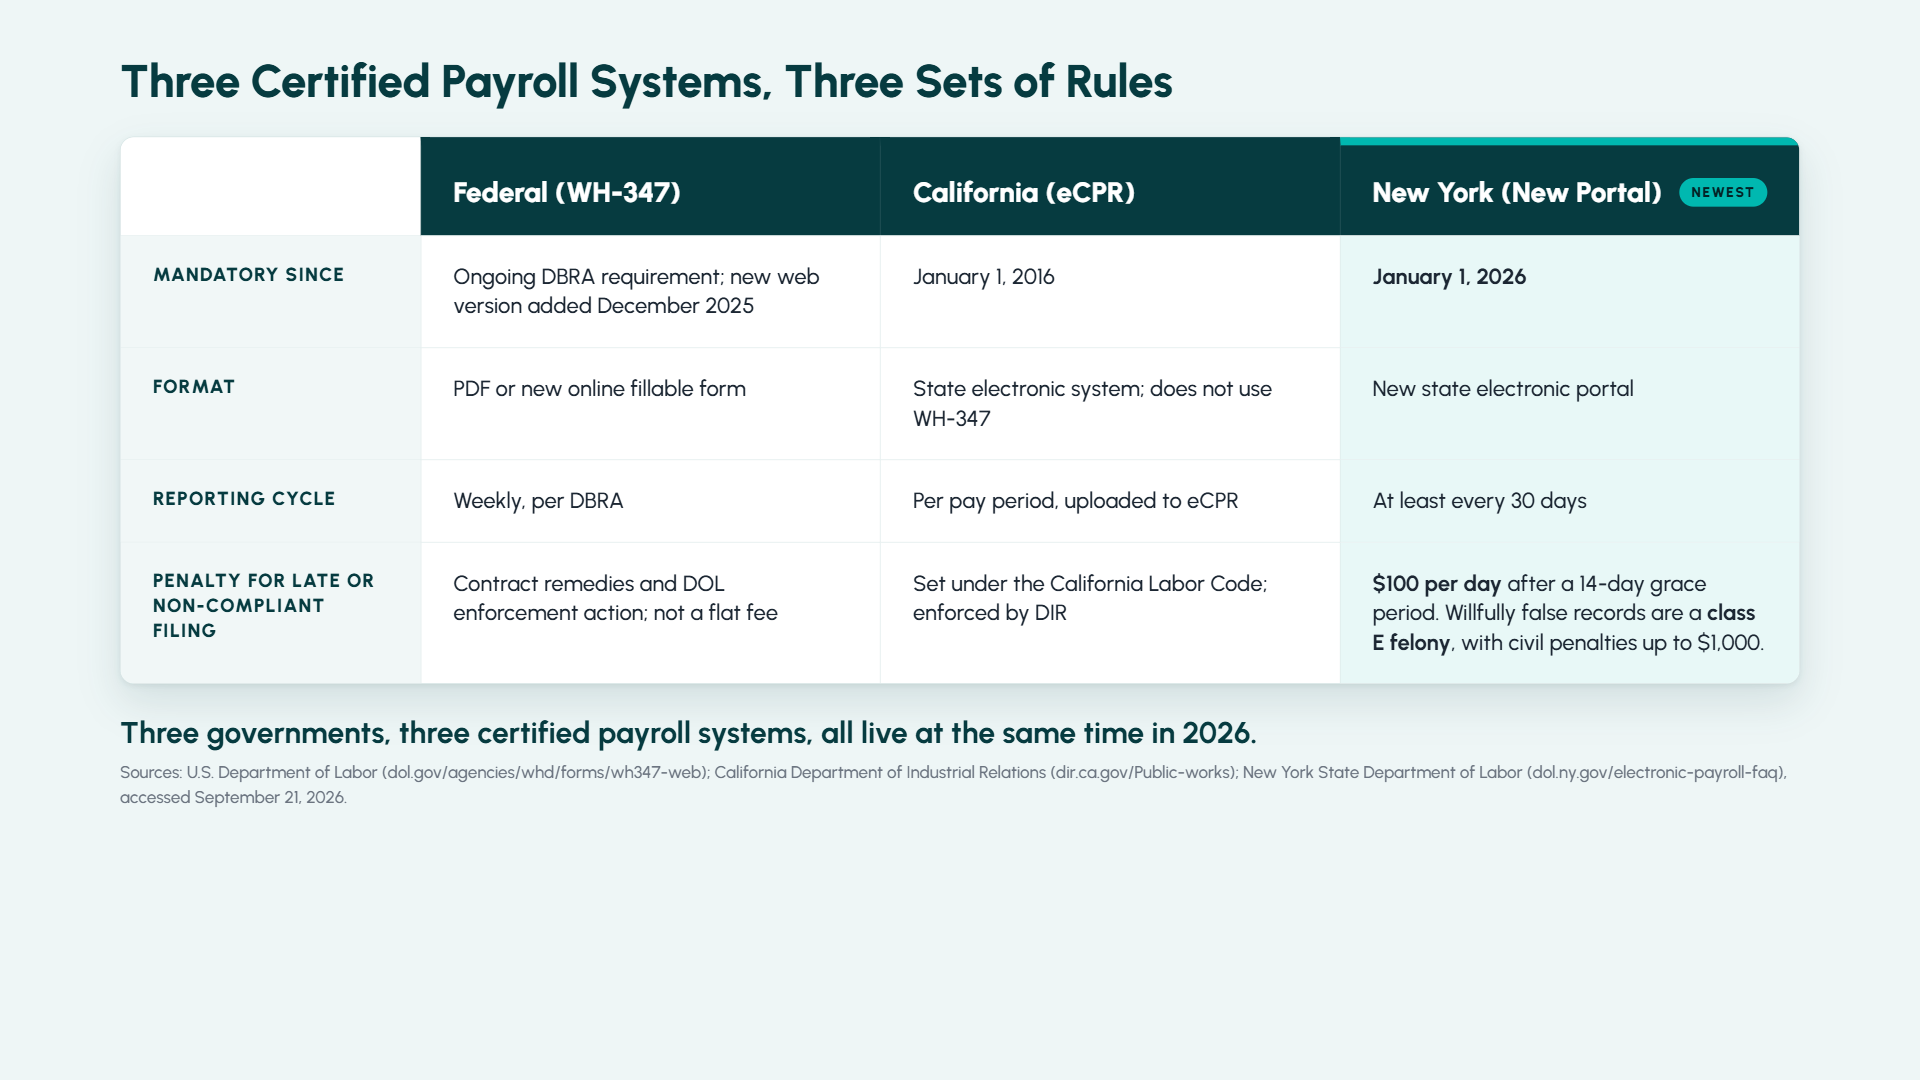
Federal contractors have used Form WH-347 for decades, and the Department of Labor gave it its first real interface update in December 2025: an online fillable version at dol.gov, built to catch the errors contractors made filling in the PDF by hand. It works in a browser, nothing gets installed, and the department says the data stays on the user’s machine rather than a DOL server. The older PDF is still valid. Using either version is optional; submitting accurate weekly certified payroll is not.

States were not waiting on Washington to modernize their own systems. California has required contractors on public works to file through its own electronic certified payroll reporting system, eCPR, since January 1, 2016, and the federal WH-347 does not enter into it at all. New York went further in the other direction. Starting January 1, 2026, contractors and subcontractors on New York public work and on many privately funded prevailing wage projects have to submit certified payroll through a new state portal at least every 30 days, with a $100-per-day penalty kicking in after a 14-day grace period for late submissions, and separate criminal exposure for knowingly false records.

Three governments, three different systems, three different cadences and formats, and that is before a contractor works across county-level or agency-specific wage determinations on top of it. A construction ERP that assumes certified payroll means one form, filled out one way, is already behind.

What DOL’s Enforcement Numbers Actually Show

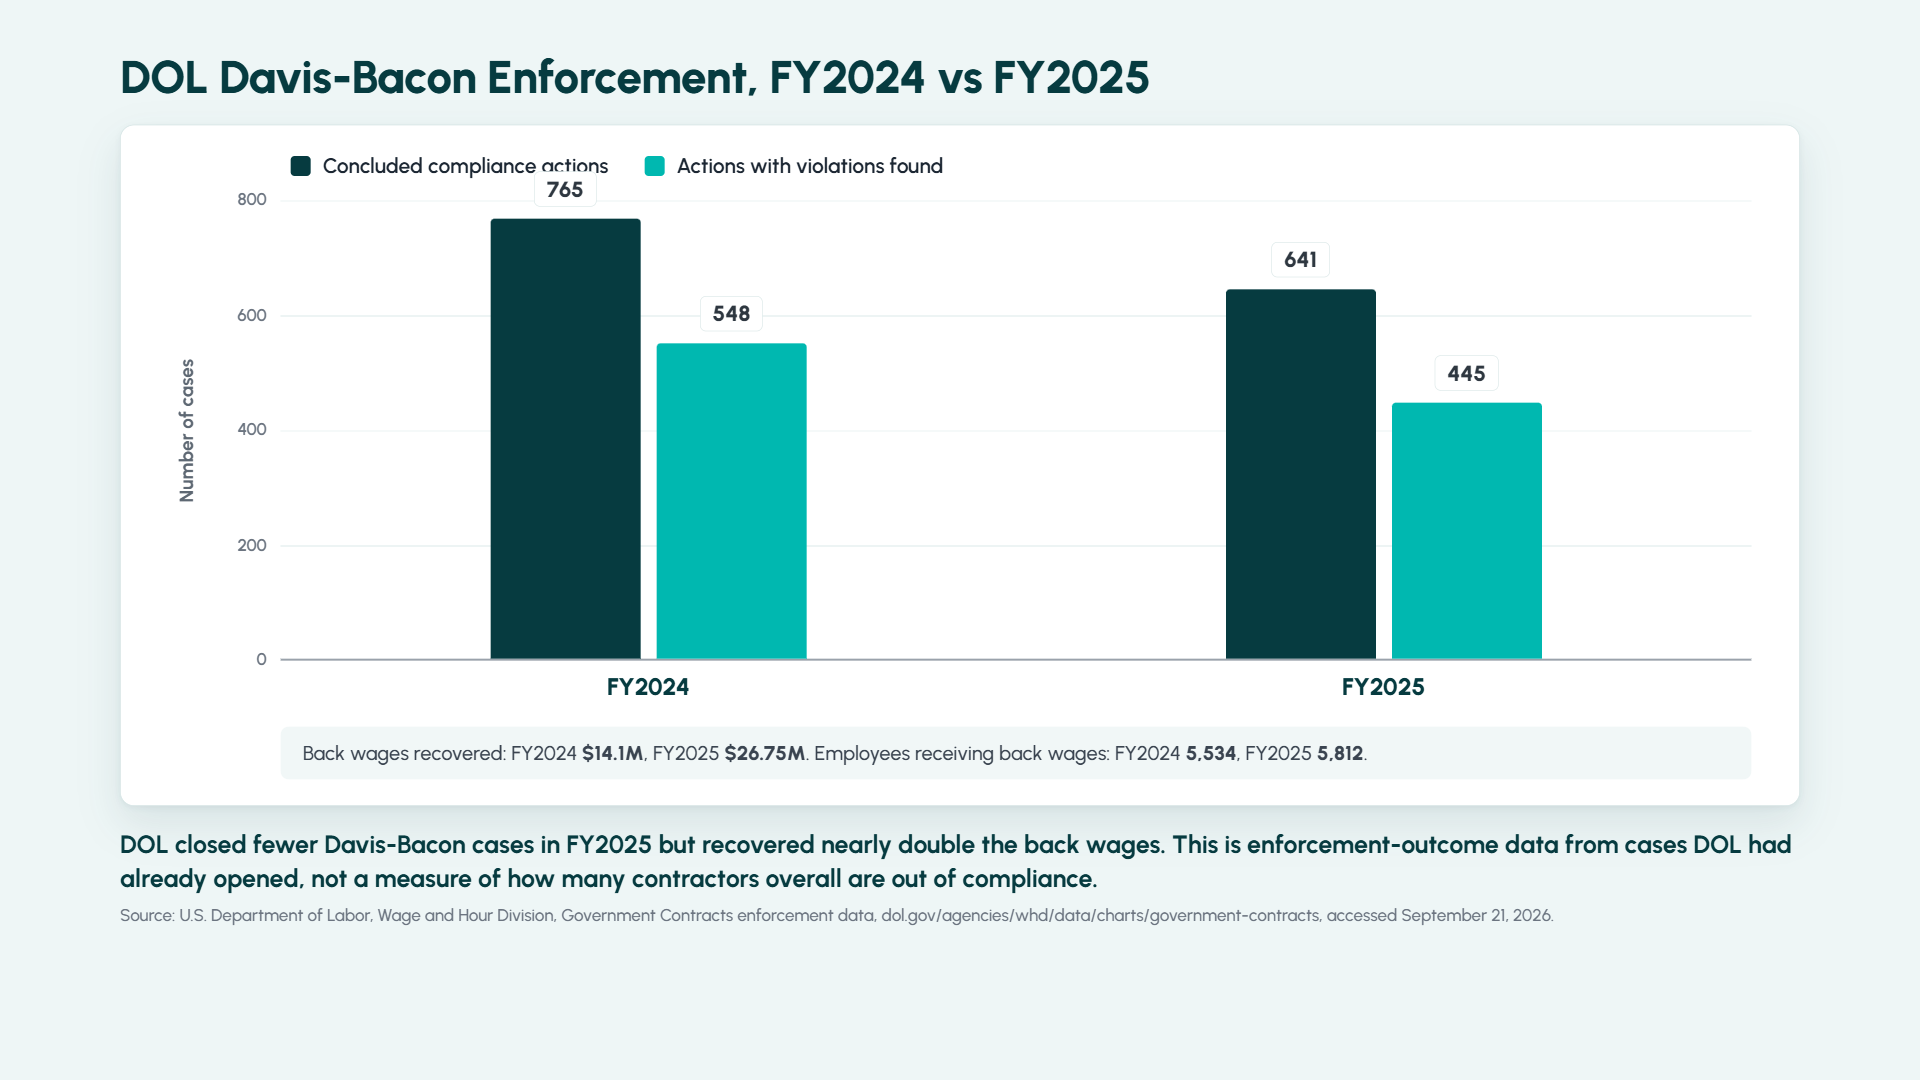
The Department of Labor’s Wage and Hour Division publishes its own enforcement results by act, and the Davis-Bacon and Related Acts numbers for fiscal year 2025 are worth reading carefully, in both directions. WHD closed 641 DBRA compliance actions in FY2025 and found violations in 445 of them, about 69%, recovering just over $26.75 million in back wages for 5,812 employees. In FY2024, WHD closed 765 actions, found violations in 548, about 72%, and recovered $14.1 million for 5,534 employees.

Read those numbers for what they are, not for what they sound like. This is not a survey of the construction industry and it is not a random sample. These are outcomes from cases WHD had already opened, typically because something, a worker complaint, a referral, a targeted review, flagged the contractor for investigation in the first place. A 69% violation rate among investigated cases says something about how hard the details are to get right once an investigator starts pulling records. It says nothing about what percentage of contractors overall are out of compliance, and it should not be quoted that way.

What the two years do show consistently is that when DOL looks, it tends to find something, and the dollar recovery moved up sharply even as the case count went down. That combination, fewer cases opened, more money recovered per case, points to violations that were not small clerical slips.

Construction ERP Compliance: Where ProjectPro Fits

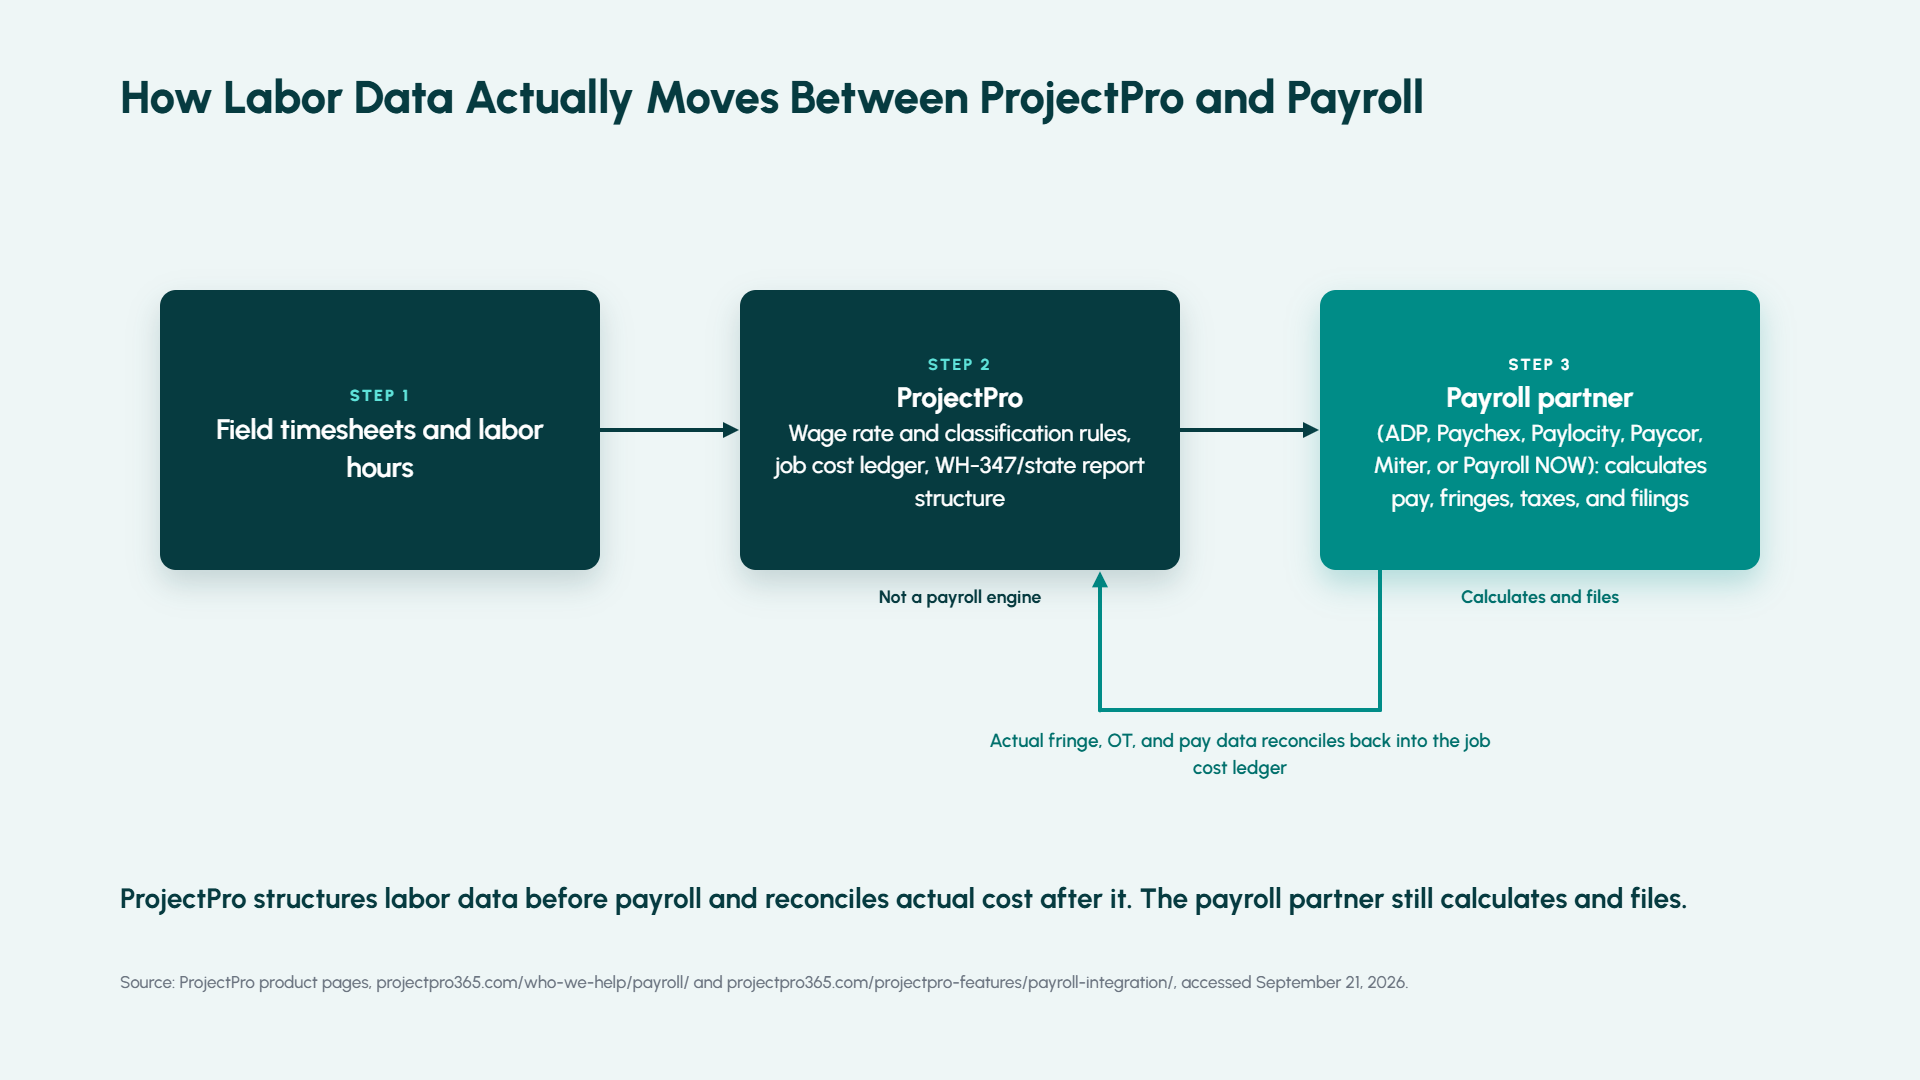
ProjectPro, Netsmartz’s construction ERP built on Microsoft Dynamics 365 Business Central, does not run payroll, and says so plainly on its own product pages. It works alongside outsourced payroll providers rather than replacing them, naming integrations with ADP, Paychex, Paylocity, Paycor, and Miter, plus a tighter path to Integrity Data’s Payroll NOW for firms that want payroll running inside Business Central itself. Fringe benefits, tax withholding, and the actual filing work stay with whichever payroll partner a contractor uses. In that sense, ProjectPro is not certified payroll software in the way a standalone payroll engine is: it does not calculate or file on a contractor’s behalf.

What ProjectPro is built to do sits on either side of that payroll run. On the front end, it maps labor codes to project wage rates by location and classification, so hours get categorized correctly (straight time, overtime, fringe-eligible or not) before they ever reach the payroll system. On the back end, once the payroll partner has calculated actual pay, fringes, and overtime, that data reconciles back into ProjectPro’s job cost ledger, so the labor burden on a certified payroll job shows up correctly against the right cost code. ProjectPro’s own materials describe generating WH-347 and state-format reports from that structured labor data, applying the wage and fringe rules that were set up on the front end.

What that does not mean is auto-filing with a state agency. Nothing in ProjectPro’s public materials claims a direct integration with California’s eCPR system or New York’s new portal specifically, and a contractor using either state’s system should confirm the export format and filing process with their implementation team rather than assume it is handled. The honest version of this story is data readiness and reporting structure, not a payroll engine and not a state filing service.

The Signature Is the Risk

Every certified payroll report still ends the same way it did when Form WH-347 was a typewritten page: someone signs it, and that signature is a legal statement, not an administrative formality. What changed in the last year is how many different systems that signature now has to satisfy: a federal web form that is optional but does not replace the underlying weekly obligation, a California system that has run independently for a decade, and a New York portal that started enforcing its own 30-day cycle and daily penalty on January 1, 2026.

For a CFO or controller, the practical question is not whether an ERP claims to handle certified payroll. It is whether the wage rates, classifications, fringe treatment, and apprentice ratios feeding that report are correct before anyone signs anything, and whether the system can prove it if an investigator asks. That is a data problem before it is a compliance problem, and it is worth auditing before the next bid, not after the next investigation.

Next Step

If certified payroll reporting on your Davis-Bacon or prevailing wage jobs still runs on spreadsheets, or on wage and classification data nobody fully trusts before it reaches payroll, it is worth a short conversation about what a structured job cost and wage data setup looks like in ProjectPro. Talk to the ProjectPro team at projectpro365.com to walk through your current process before your next audit or bid.

FAQs

Certified payroll is the weekly wage reporting required on federal Davis-Bacon projects and most state prevailing wage jobs. Each week, a contractor reports every covered worker’s hours, classification, wage rate, and fringe benefit treatment for that specific project, then signs a Statement of Compliance certifying the data is accurate and complete.

A normal payroll run pays employees on whatever cycle a company uses, often biweekly, and reports wages in aggregate. Certified payroll requires weekly reporting tied to a specific project, wage rates set by a government wage determination rather than a company’s standard pay scale, and a signed legal certification, not just a pay stub.

No. Some states accept the federal WH-347 form or a close variant, but others run entirely separate systems. California has required contractors to file through its own eCPR system since January 1, 2016, and New York started requiring submissions through a new state portal on January 1, 2026. A contractor working across state lines may need to satisfy more than one format inside the same company.

It is the signed certification section of Form WH-347, or the equivalent on a state form. Signing it certifies that the payroll data for that week is correct and complete, that supporting records are available on request, that reported classifications match the work performed, that any apprentices are properly registered, and that no improper deductions were taken from workers’ pay.

Generally, no. Certified payroll software and construction ERPs typically manage job costing, wage classification, and report generation, while a payroll provider, such as ADP, Paychex, or Paylocity, calculates actual pay, withholds taxes, and handles fringe benefit contributions. The two systems are meant to work together, with labor data flowing one way and actual pay and fringe data reconciling back the other way.

CFMA 2026 Member